FMCG distributor margin vs ROI: calculating per-brand return on capital with shared costs, credit days and pending claims
Distributor ROI Calculation: Why FMCG Distributor Margin Lies
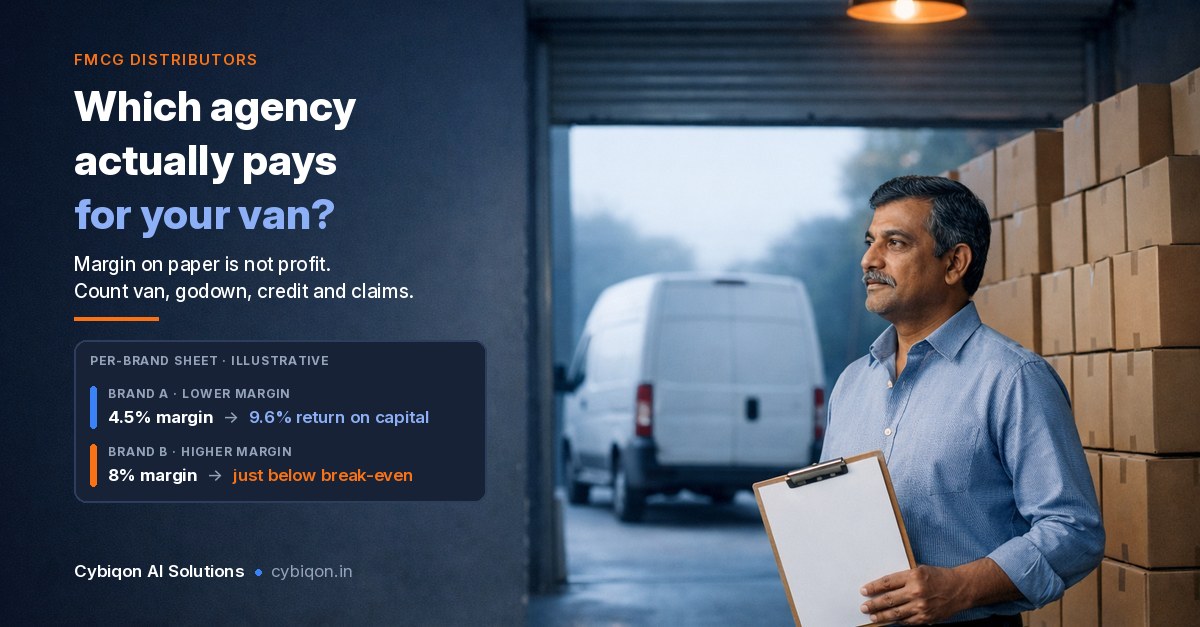
Ask the owner of a three-agency distributorship in Indore or Coimbatore which brand makes him the most money, and he will usually quote the scheme letter: "the food brand gives me 8%, the soap company gives 4.5%." That is the FMCG distributor margin on paper. It is not what the brand earns him once the van, the salesmen, the credit days and the unsettled claims are paid for. A proper distributor ROI calculation often gives a different answer.
The pressure is real. In June 2026 the All India Consumer Products Distributors Federation (AICPDF), which says it represents over 4.5 lakh distributors in 25 states, told FMCG companies that 3.5–5% margins no longer cover costs or a reasonable return. AICPDF says that by its internal assessment up to ₹57 of every ₹100 "earned" goes on logistics, basic manpower and secondary transport alone, according to Business Today.
This guide covers what margin actually means, a formula for ROI on capital, a worked two-brand example where the higher-margin brand loses money, what Tally shows per brand and where it stops, and a sheet you can build this week.
What is the FMCG distributor margin in India?
There is no single figure for FMCG distributorship profit margin in India, and anyone quoting one is quoting a particular company and channel. AICPDF frames the problem around the 3.5–5% range. Other published figures vary: one report, citing unnamed sources, put a newer entrant at 6–8% against the usual 3–5%. Regional brands sometimes offer more on paper.
The best-documented example is Hindustan Unilever's restructuring between December 2023 and May 2024, reported by The Core. It is background from 2024, not current news, but it shows how an HUL distributor margin is now built:
| HUL margin component | Before | After |
|---|---|---|
| Urban fixed | 3.9% | 3.3% |
| Urban variable | 0.7% | 2.0% |
| Urban total potential | 4.6% | 5.3% |
| Rural fixed | 5.0% | 3.6% |
| Rural variable | 0.4% | 1.7% |
| Rural total | 5.4% | 5.3% |
What is the difference between fixed and variable margin?
Fixed margin is paid on what you sell, whatever happens. Variable margin is paid only if you meet the company's service conditions; in HUL's case these were reported as 24-hour delivery, using HUL's software, outlet coverage and pushing new packs. AICPDF asked for 5% fixed. Distributors in Maharashtra began boycotting HUL products on 11 Jan 2024, starting with Taj Mahal tea, as IndianTelevision reported.
The practical point: your "5.3%" is only 5.3% in the months you hit every condition. Budget on fixed, treat variable as upside.
Why do FMCG distributors say 3.5–5% margins are not enough?
Because a margin is a percentage of sales, and almost every cost a distributor carries is not. The van costs the same whether it carries ₹40,000 of soap or ₹40,000 of biscuits. The salesman's salary does not shrink when a principal cuts a slab. Retailer credit gets longer when the market is tight.
AICPDF's own breakdown says up to ₹57 of every ₹100 earned goes to logistics, manpower and secondary transport, and that is before warehousing, bank interest, compliance and product damage. AICPDF says many distributors are at a practical loss. Outlook Business, citing PTI, reported that the federation set companies a 30 Jul 2026 deadline and warned of protests in August. The deadline passed without a publicly reported settlement.
Channels are shifting under that too. E-commerce, mostly quick commerce, was about 21% of FMCG sales in the top eight metros in April–June 2026, up from 18% in October–December 2025, per NIQ data reported by BusinessLine and The Pioneer. In southern metros it was 25%. Traditional trade still carries the bulk nationally (about 81% in the same reporting), but a metro distributor's best outlets are the ones being skimmed. AICPDF has also complained to the CCI about Blinkit, Zepto and Instamart; the CCI opened a preliminary inquiry in June 2025, and those remain allegations with no ruling.
Distributors do walk away. NSE-listed Shanthala FMCG withdrew from its ITC distributorship on 13 May 2026, held since 2007, according to its exchange filing, which gives no reason.
The distributor ROI calculation formula
Margin tells you how much you keep from each rupee of sales. ROI tells you how much you earn on the money you have locked into the agency. Two brands with the same margin can have very different ROI, because one turns its stock in two weeks and the other sits in the godown for a month and then on the retailer's books for three more weeks.
The distributor return on investment formula worth using:
- ROI on capital = net margin % × (annual sales ÷ capital employed)
- Capital employed = (stock days + retailer credit days − company credit days) × daily sales + pending claims + deposits and vans
Net margin is the brand's margin and schemes, minus every cost the brand causes: its share of salesmen, vans, godown, damage and expiry, and interest on its capital.
Three items get missed in almost every sheet:
- Retailer credit days. If a brand's outlets pay in 21 days, you are funding three weeks of its sales. Your ageing analysis in Tally Prime tells you what that number really is, brand by brand, if your ledgers allow it.
- Company credit days. A principal that wants payment in advance costs you more capital than one that gives 15 days.
- Pending claims. A scheme you have passed to retailers but the company has not yet reimbursed is your money, sitting with them. Slow scheme claim settlement is a capital cost, not just an accounting nuisance.
A worked distributor ROI calculation: the higher-margin brand that loses money
This is our own illustrative arithmetic, not a client's figures. Say a distributor runs two agencies from one godown, and charges an assumed 11% a year on capital (standing in for an overdraft rate, or what the money could earn elsewhere). The question is FMCG distributor profit per brand, after everything.
- Brand A, a national home and personal care company: ₹4.8 cr a year, 4.5% margin including schemes, 15 days of stock, 12 days retailer credit, and the company wants payment in advance.
- Brand B, a regional food brand: ₹1.2 cr a year, 8% margin, 30 days of stock, 21 days retailer credit, 15 days credit from the company.
No security deposits, and vans are on hire, so they sit in costs.
| Line | Brand A | Brand B |
|---|---|---|
| Annual sales | ₹4.8 cr | ₹1.2 cr |
| Margin + schemes | 4.5% = ₹21.6L | 8% = ₹9.6L |
| Salesmen + van | ₹9L | ₹5L |
| Godown share | ₹3L | ₹1.5L |
| Damage / expiry | 0.3% = ₹1.44L | 1.5% = ₹1.8L |
| Net working days funded | 15 + 12 − 0 = 27 | 30 + 21 − 15 = 36 |
| Capital in stock and credit | ≈ ₹35.5L | ≈ ₹11.8L |
| Pending claims | ₹4L | ₹1L |
| Capital employed | ≈ ₹39.5L | ≈ ₹12.8L |
| Interest at 11% | ≈ ₹4.35L | ≈ ₹1.41L |
| Net profit | ≈ ₹3.8L | ≈ −₹0.1L |
| ROI on capital (after the 11%) | ≈ 9.6% | ≈ −0.9% |
Run it through the formula as a check. Brand A: net margin ≈ 0.79% × (₹480L ÷ ₹39.5L ≈ 12 turns) ≈ 9.6%. Brand B: ≈ −0.09% × about 9.4 turns, just below zero.
Brand B looks nearly twice as good on the scheme letter and in Tally's gross profit report. It needs its own salesman and van for a quarter of the volume, its stock sits twice as long, its expiry rate is five times higher, and its outlets pay slowly. After paying for the money it ties up, it earns nothing. Brand A, the one the owner grumbles about, is carrying the business.
Change the inputs and the answer changes, which is the point: CalcGuru's published model of a ₹12 cr distributor shows about 4.3% ROI on ₹1.11 cr invested, rising to about 23% in the same model after adding a second principal and cutting retailer credit from 14 to 8 days and stock from 18 to 13 days (CalcGuru, an illustrative model, not survey data). In both models, the days do a lot of the work.
How can I see brand-wise profit in TallyPrime?
Out of the box you get more brand wise profitability in Tally than most owners use, but it stops at gross profit.
- Stock Summary with F7 (Show Profit) gives gross profit on outward stock by item or stock group, per Tally's help. If each principal is its own stock group, this is your stock group wise gross profit in Tally Prime: sales minus cost of goods, per brand.
- Cost centres and cost categories let you allocate expenses in parallel, for example one category for salesmen and another for schemes, with Cost Centre Breakup and Summary reports (Tally help).
- Stock Group Cost Analysis is described in the Tally.ERP 9 documentation as bringing direct and indirect expenses against sales per group (Tally.ERP 9 docs). Check the TallyPrime path with your Tally partner before relying on it.
What Tally does not do natively: split a shared van or godown across brands by a rule you choose, charge interest on the capital each brand ties up, or treat pending claims as capital. So the gross profit report ranks Brand B above Brand A, and nothing in the standard reports corrects it.
How do I allocate salesman and van costs to each brand?
Cost centre allocation for salesmen in Tally works when a salesman is dedicated to one principal; book his salary to that brand's cost centre. Shared costs need an allocation key, and the key should follow what drives the cost:
| Shared cost | Sensible allocation key |
|---|---|
| Van and driver | Drops or cases delivered per brand |
| Shared salesman | Share of beat time, or lines booked per brand |
| Godown rent and staff | Floor space or average cases held |
| Damage and expiry | Actual write-offs by brand, not a flat % |
| Interest | Each brand's capital employed (formula above) |
Do not split by sales value. That quietly loads big-turnover brands with costs the small ones cause. If your salesmen book orders on an app, the salesman order booking app data already records lines per brand per outlet, which is the cleanest key you will get.
A free first step: the per-brand cost sheet
Export four things from Tally each month: Stock Summary by stock group (with profit), Cost Centre Breakup, outstanding ageing by party, and your claim register. In a sheet, give each brand a column and these rows: sales, gross margin, schemes received, schemes pending, dedicated salesmen, allocated van, allocated godown, damage and expiry, stock days, retailer credit days, company credit days, capital employed, interest, net profit, ROI. Write the allocation keys at the top so the numbers can be argued with. One quarter of this sheet is stronger negotiating material than a complaint about margins.
Should a distributor drop a low-margin FMCG agency?
Not on the margin alone, and not on one bad month. Use the ROI number, then work through the levers in order:
- Days first. Cutting retailer credit or stock days on a slow brand often turns it positive without touching the margin, as both examples above show.
- Claims. Chase the pending scheme claims; that money is capital you are lending the company free.
- Costs. Can the brand share a van and salesman instead of having its own?
- Negotiate with numbers. A principal's area manager can ignore "the margin is too low". It is harder to ignore "your brand ties up ₹12.8 lakh of my money and earns nothing after interest, here is the sheet".
- Exit only if none of that works, and plan for the capital it releases.
Keeping a loss-making agency "for the relationship" is a decision you can make, but make it knowing what it costs.
When a distributor ROI calculation in a sheet stops being enough
The sheet works while one person rebuilds it by hand every month. It breaks when that person is busy at quarter end, when nobody updates claim status, or when you add a fourth principal and a second godown. That is the same moment described in signs your business has outgrown Excel: the numbers exist, but only one person can produce them, and only late.
FAQs
What is the margin of an FMCG distributor in India?
It depends on the company and channel. AICPDF frames the problem around 3.5–5%, and HUL's 2024 structure reportedly gave up to 5.3% including variable margin tied to service conditions. Regional brands can offer more on paper. What matters is what the brand earns after its own costs.
How do you calculate ROI for a distributor?
ROI on capital = net margin % × (annual sales ÷ capital employed). Capital employed = (stock days + retailer credit days − company credit days) × daily sales + pending claims + deposits and vans. Net margin is after salesmen, vans, godown, damage and interest.
How much working capital does an FMCG distributorship need?
Use the capital formula above. On illustrative numbers, a ₹4.8 cr brand with 15 days stock, 12 days credit and advance payment ties up about ₹39.5 lakh including claims. Distributor working capital is driven by credit days and stock days more than by turnover.
How do pending scheme claims affect distributor profit?
They are money you have already passed on to retailers and not yet recovered from the company. Until settled, they add to capital employed and carry an interest cost, and claims that are never settled come straight off profit.
How Cybiqon would build this for your distributorship
If the per-brand sheet is worth having but nobody has time to rebuild it every month, this is what Cybiqon would build: a per-brand profitability dashboard that reads stock-group sales, cost-centre expenses, receivables ageing and claim status from your Tally, splits shared van, salesman and godown costs by the rules you set, and shows each agency's return on the capital it ties up, every month without anyone touching a sheet.
It is written for your brands, your beats and your allocation keys, not configured from a template, by the two founders, and you own every line of the code. Our admin panels and internal tools start from ₹29,999 one-time, scoped per build. If you want to talk it through, book a 30-minute call, call +91 9250711473, or write to [email protected].
Conclusion
The scheme letter gives you a gross figure. A distributor ROI calculation tells you which agency actually pays for its van, its salesmen and the money it locks up. Work out each brand's capital employed, charge it for the costs it causes, and the FMCG distributor margin stops being the only number in the room. Very often the brand you complain about is the one carrying the business. Start with the free sheet this month; if it proves its worth and the rebuild becomes the bottleneck, Cybiqon can build the dashboard that keeps it current.
Want this set up for your business?
Book a free call — no tech jargon, no sales pressure. Just honest answers.
What we build for this: Admin panels & internal tools